
IRS CP2000 Notice: Understand What the IRS Is Proposing
A CP2000 proposes changes based on information reported to the IRS that does not match your filed return. Before agreeing or paying, understand what the IRS changed and whether the proposed adjustment is correct.
Review My CP2000Bring the notice and its response date to a complimentary 20-minute consultation. We will discuss whether LTA is the right fit.
A proposal, not an assessed bill
The IRS Automated Underreporter process compares information from employers, lenders and other third parties with what was reported on a return. A CP2000 explains a possible difference and proposes a change. The proposal can increase tax, decrease tax or leave it unchanged.
Read the entire notice, check the tax year and information at issue, and respond by the date shown. If you disagree, explain why and include supporting documents as the notice directs. The response deadline matters even when the proposal appears wrong.
IRS guidance: Understanding your CP2000 series notice.
Cancellation of debt requires a closer look
A Form 1099-C reports a debt-related event to the IRS. Receiving one does not, by itself, settle how much canceled debt is taxable on your federal return. The underlying debt, the reported amount and the applicable tax rules all matter.
An exclusion may apply in some circumstances. For example, insolvency is measured immediately before cancellation, and the exclusion is generally limited to the amount of insolvency. Form 982 may be required to report an applicable exclusion and related tax-attribute reduction. These rules are fact-specific; a 1099-C does not mean every taxpayer qualifies.
IRS guidance: Publication 4681 and Form 982 instructions.
From a $7,233 proposal to no change
In one documented matter, three Forms 1099-C totaled $25,041. The CP2000 proposed $5,509 in additional tax, a $1,102 substantial-understatement penalty, $622 in interest and $7,233 as the proposed amount due. The IRS later acknowledged receiving the response and needing more time to review it. A subsequent CP2005 closed the inquiry with no change.
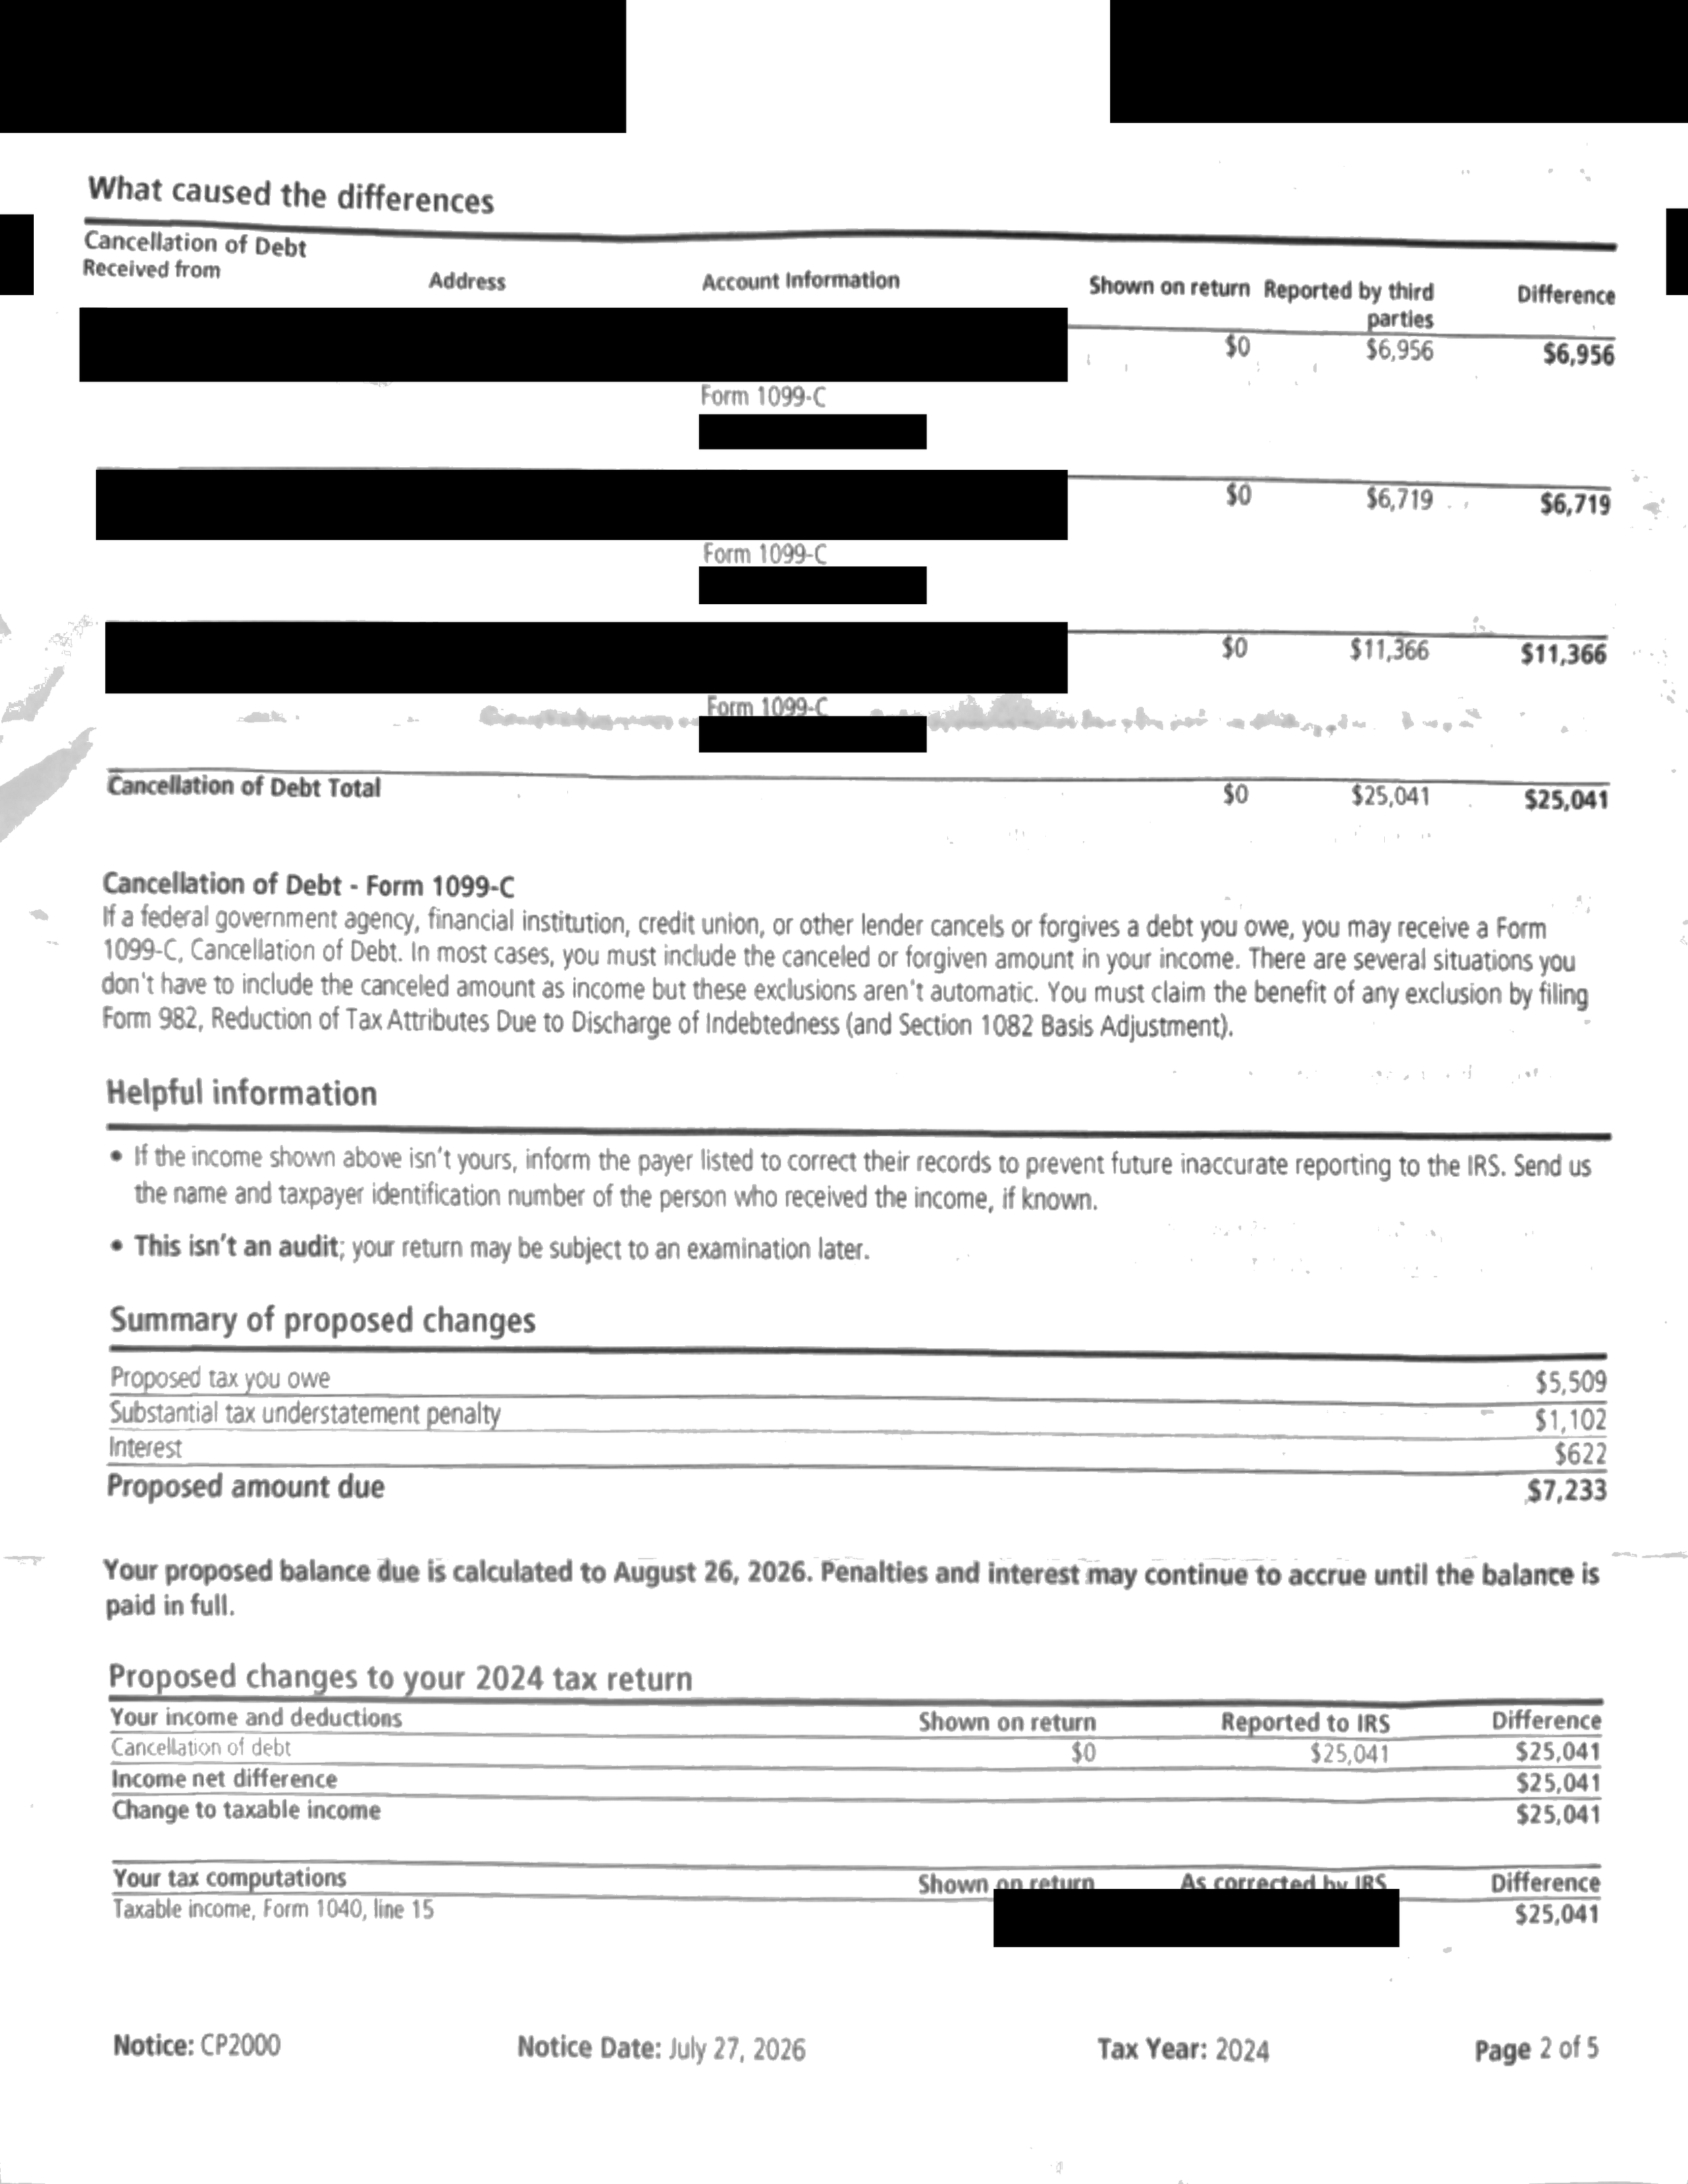
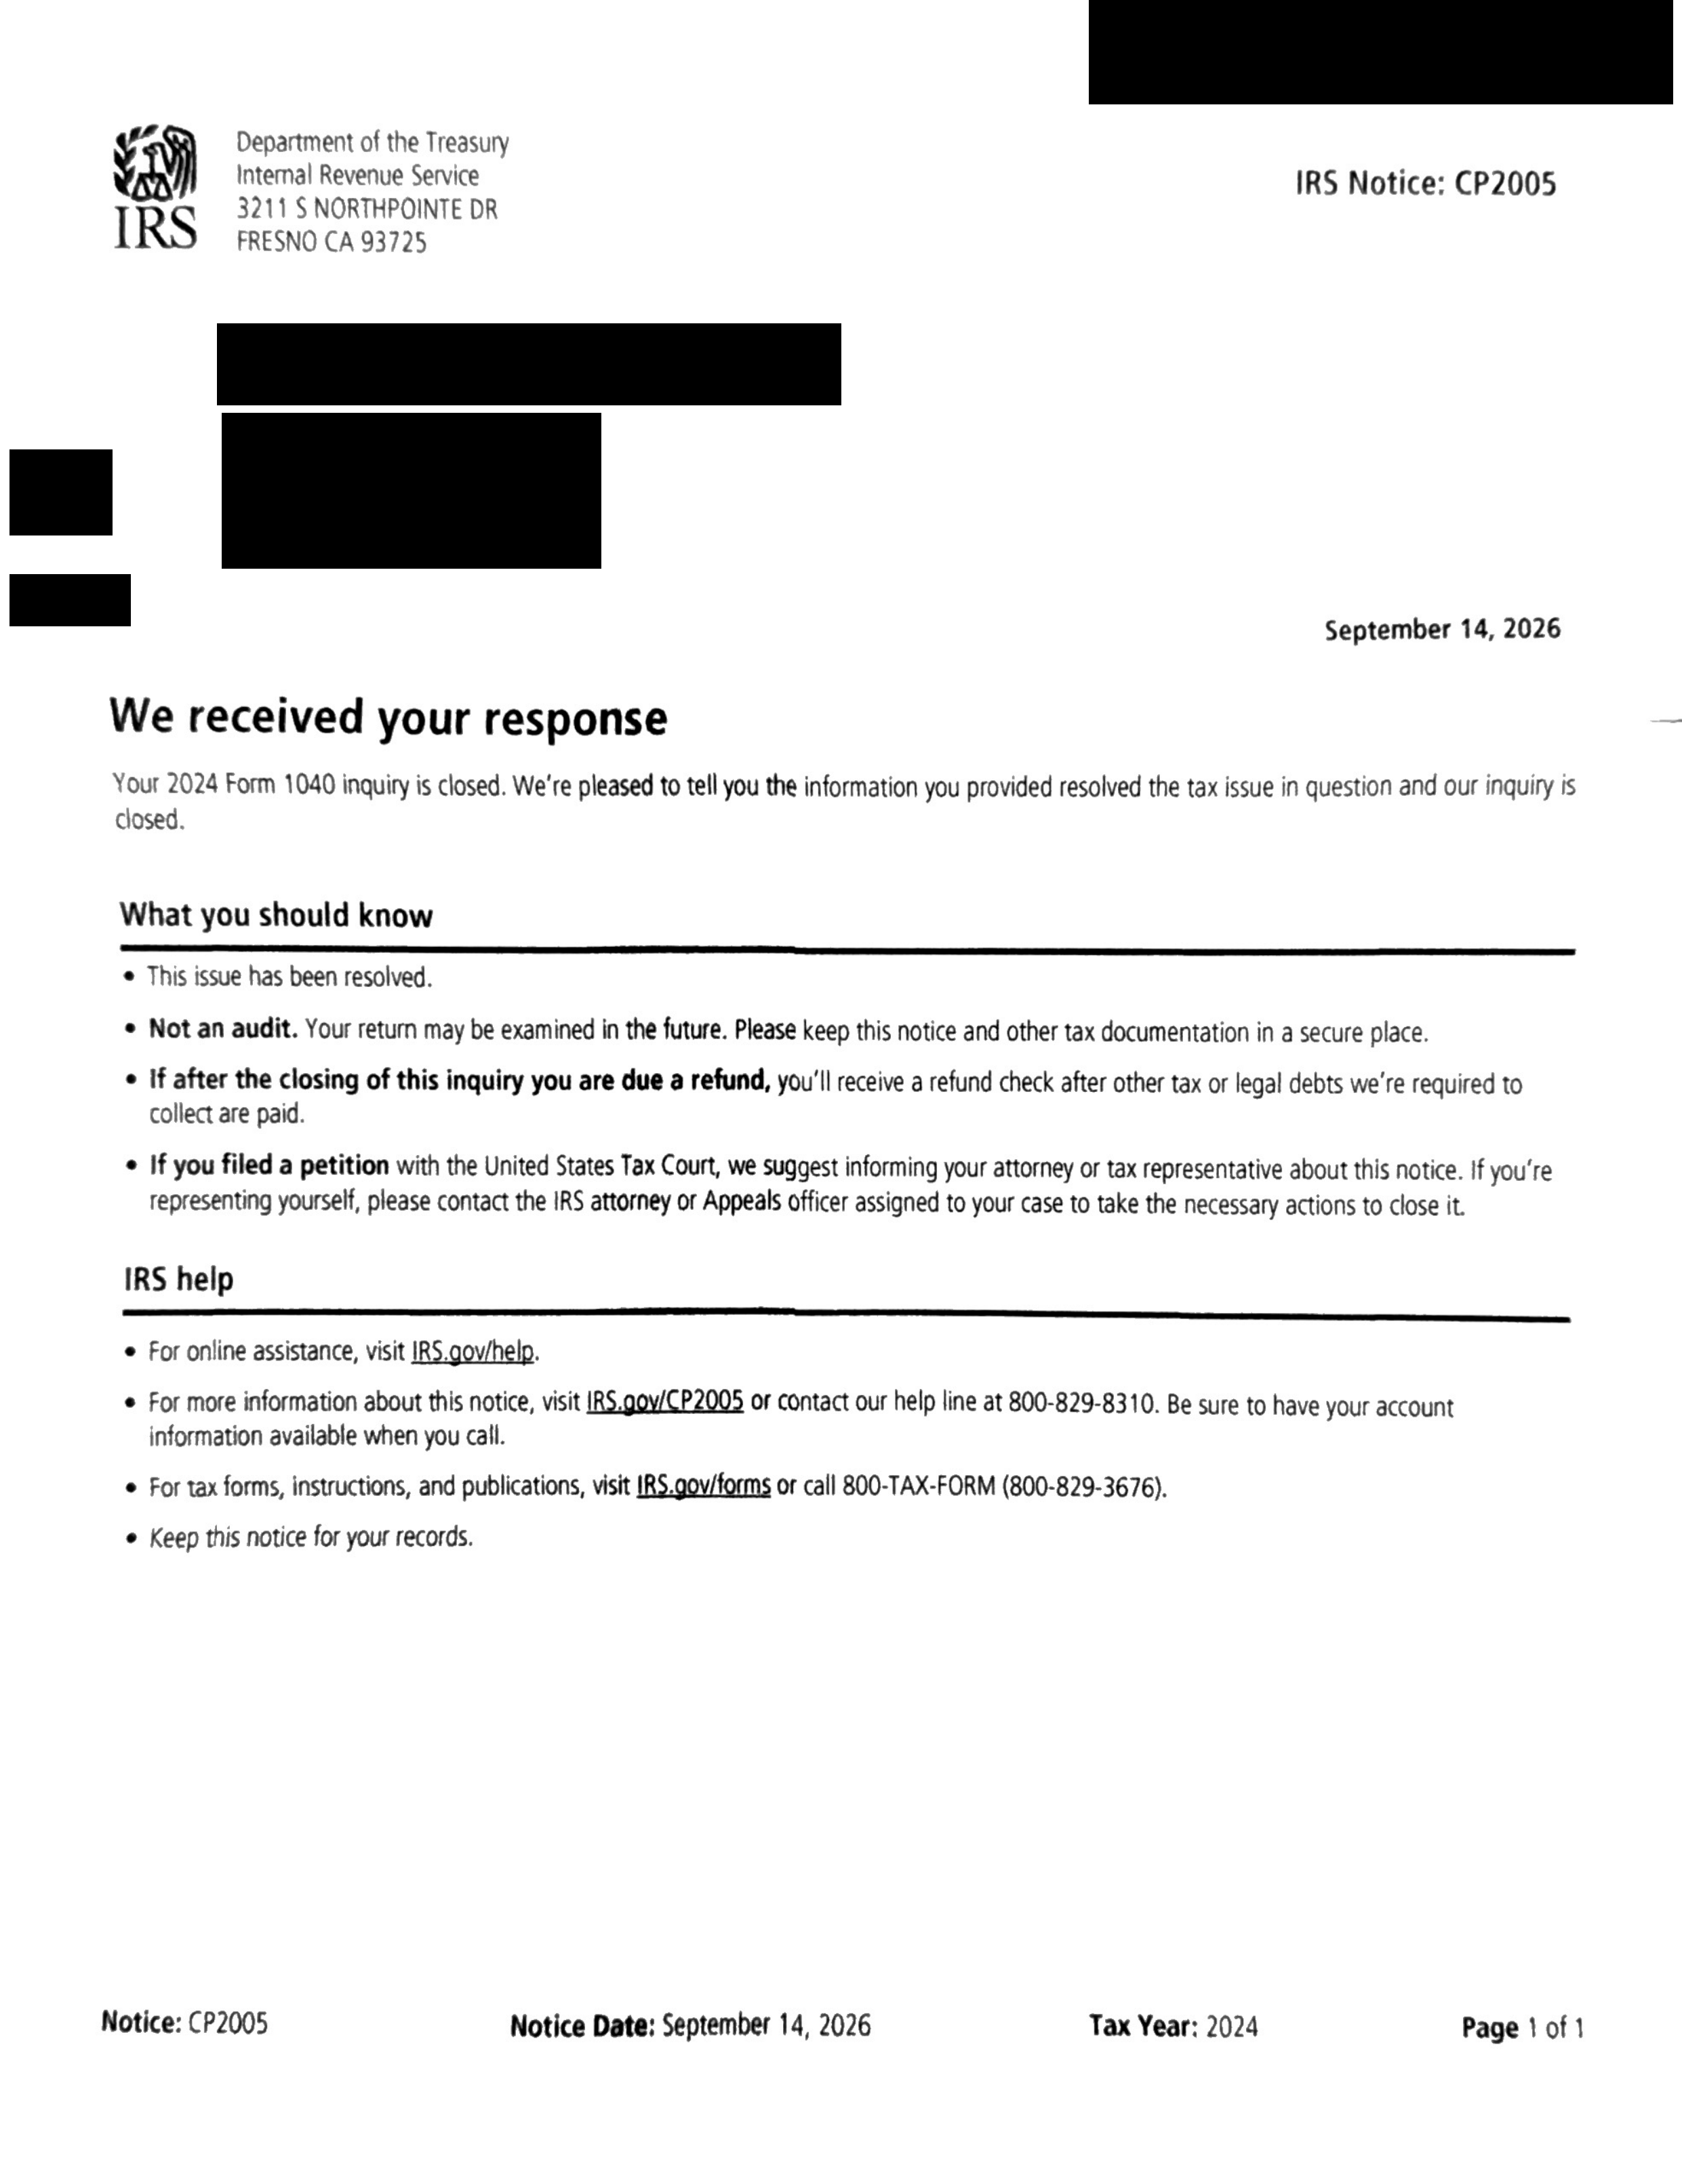
This example documents one taxpayer's correspondence and outcome. Results depend on individual facts and circumstances and do not guarantee future outcomes.
What happens when you contact LTA
Not every CP2000 requires professional representation, and not every issue falls within LTA's practice. We first identify what the IRS changed and why. If the matter is within scope, we can explain the review and response work that may help. When it calls for specialized return preparation, accounting or basis reconstruction, or another discipline outside our practice, we will say so.
Nearly 20 years of IRS experience, including Revenue Officer and supervisory assignments. Brandon Lynch, EA, applies a Strategy Over Force™ approach: understand the notice and supporting facts before choosing a response.
For broader IRS account or collection concerns, see our IRS tax resolution overview.
Review My CP2000Updated September 2026 · Brandon Lynch, EA · General educational information, not individualized tax advice. LTA is a private firm and is not affiliated with the IRS.